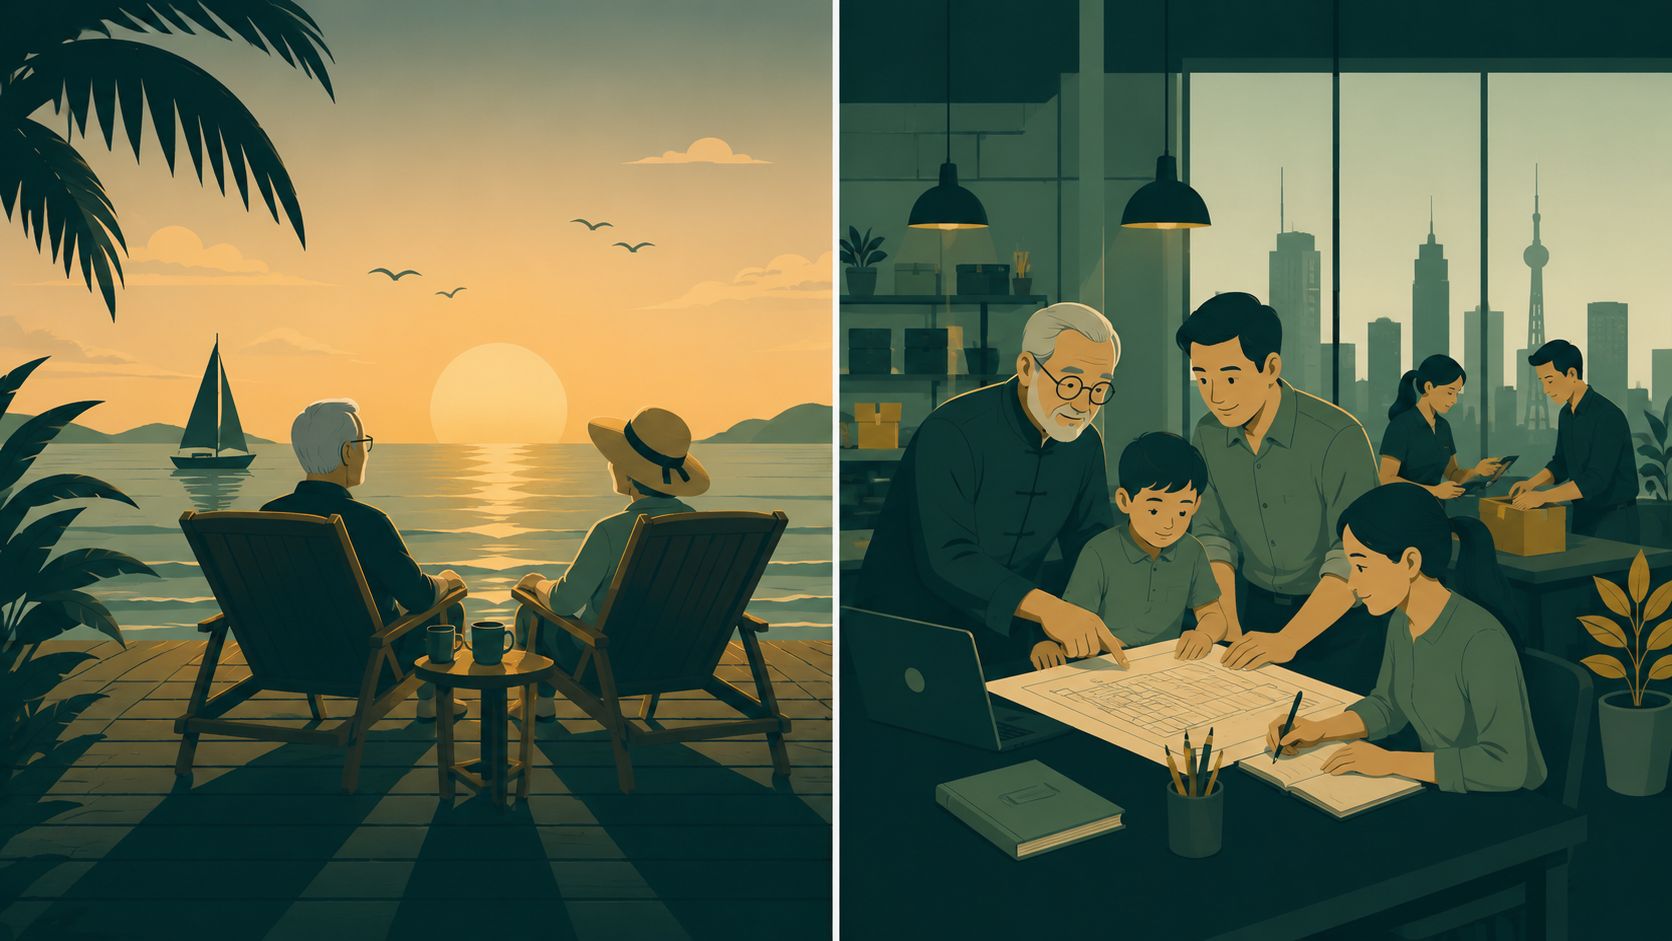
One culture asks, "When can I retire?" Another asks, "How do I keep creating value?"
That single difference in mindset might explain why some people build real wealth - while others spend decades waiting for permission to enjoy it.
In this article:
Why "when can I retire?" is the wrong question to build wealth around
What Asian ownership culture gets right that Europe often misses
Where extreme work culture becomes counterproductive
The uncomfortable questions worth asking about your own financial plan
What this means if you're already building serious wealth
Most of us assume wealth comes down to earning well, investing wisely, and spending less than we make. I believed that too - until I spent time in Thailand and started noticing something deeper: how much of our financial thinking is shaped by the culture we grew up in.
The longer I stayed, the clearer it became. Many Westerners and many Asians weren't just earning money differently. They were playing entirely different financial games.
Growing up in Lithuania, the path felt almost prewritten:
About the author
Tomas Vyšniauskas is a professional trader and founder of Sovereign Prosperity.
Trading full-time since 2021, he manages capital with a focus on disciplined growth and controlled downside.
His work is built around a simple goal: helping people make their existing capital work harder without sacrificing the freedom that wealth is supposed to create.
The plan: study hard, land a stable job, contribute to your pension, save steadily, invest conservatively, work for forty-plus years, then retire - hopefully.
What it built: real stability, and one of the highest standards of living in human history.
What it isn't: wealth. Stability and wealth are not the same thing.
The more time I spent in Asia, the more I noticed a different philosophy running underneath daily life. Instead of asking "when can I stop working?", people seemed to ask "how do I keep creating value?"
That one shift changes everything.
Europe builds toward retirement by default
Across much of Europe, retirement is treated as the ultimate financial destination.
The system: governments push pension contributions, employers offer retirement plans, and financial advertising centers on preparing for "life after work." Most conventional investment advice is really just a roadmap for accumulating enough to eventually stop.
The upside: Europe has built genuinely impressive social safety nets that reduce uncertainty and give millions of people real peace of mind.
The catch: every system shapes behavior. If you believe your future security will come mainly from pensions, employer benefits, and long-term conventional investing, you naturally spend less energy building independent wealth. Your financial life ends up depending heavily on institutions.
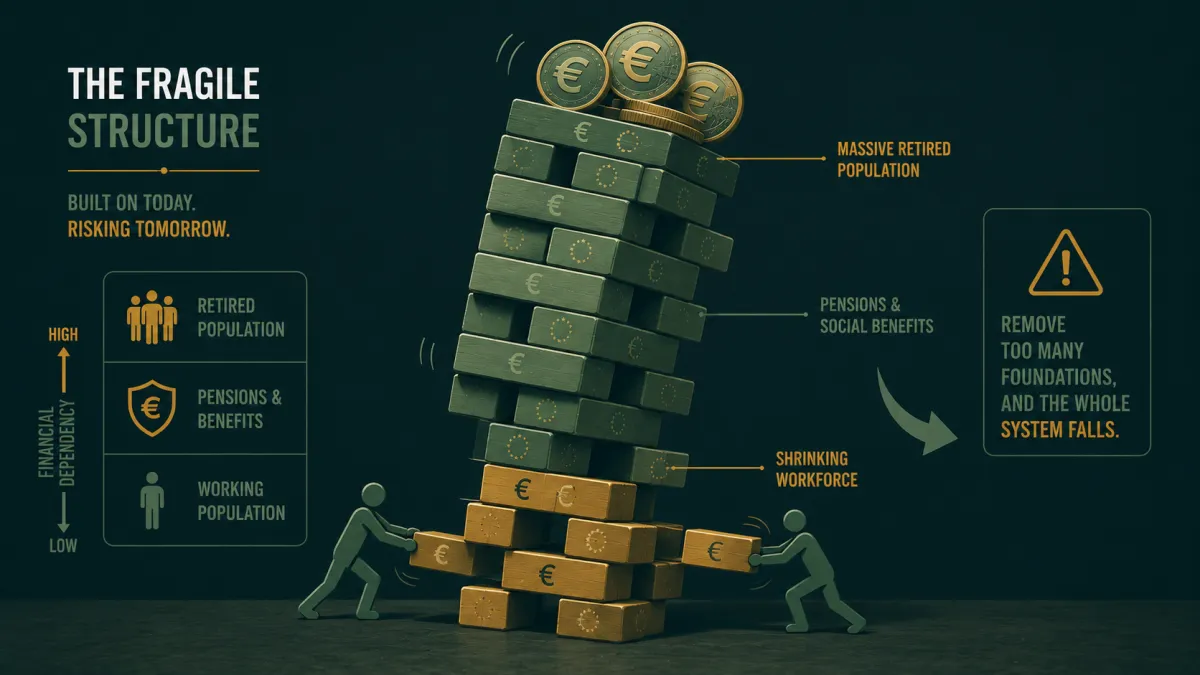
You're trusting governments to stay financially stable. You're trusting pension systems to survive demographic shifts. You're trusting markets to deliver average returns over several decades. You're trusting inflation not to quietly erode what you've saved.
Sometimes that trust pays off. Sometimes it doesn't. History is full of governments that changed course, tax systems that got rewritten, pension rules that shifted, and decades-long stretches where markets simply disappointed.
So here's the uncomfortable question every ambitious professional should ask: if the institutions around you changed dramatically tomorrow, would your financial future still hold up?
If the honest answer is no, your wealth might not be as independent as you think.
Asia often thinks differently about financial security
One of the first things that struck me in Thailand wasn't a skyscraper or a shopping mall. It was the small businesses.
Walking through neighborhoods late at night, I kept passing family-run shops that were still open - grocery stores, restaurants, repair shops, clothing stalls, barbershops. Many owners lived directly above their business. Downstairs was where they made a living. Upstairs was where they slept. Business wasn't separate from life. It was life.
Coming from Europe, where shops close early and evenings are reserved for leisure, the contrast was hard to miss.
The trade-off, honestly: fourteen-hour days come with real costs - less leisure, less free time, more pressure. I'm not romanticizing it. Europe has plenty to be proud of precisely because people aren't expected to grind endlessly.
What stuck with me instead: the mindset. The small business owners I met weren't counting down to retirement. They were building something that could keep producing income year after year - a shop, a restaurant, a family business passed down for generations. The focus wasn't on being employed. It was on owning something.
Ownership creates options. Employment creates income. Those aren't the same thing.
A moment that changed how I thought about money
One experience in Thailand has stayed with me ever since.
I went for a haircut. The barber did a perfectly normal job, we chatted a little, and right at the end, without missing a beat, he asked if I wanted an extra service too - a blowjob. It cost exactly the same as the haircut.
As someone from Lithuania, I was completely stunned. Back home, that would be almost unimaginable. Most people would see it as a deeply unacceptable way to earn money.
The barber, meanwhile, wasn't embarrassed. He wasn't pushing it on me. He asked the way you'd ask whether I also wanted my beard trimmed. I politely declined, paid for the haircut, and left.
The interesting part wasn't the offer itself. It was what it revealed about a completely different attitude toward commerce.
Why did I immediately file one way of earning money under "morally unacceptable," while he seemed to see it simply as another service some customers might voluntarily pay for?
I don't pretend to have the full explanation. Maybe it's religion. Maybe it's history. Maybe it's economic development, education, or family tradition.
But after time in both Europe and Thailand, I couldn't shake the feeling that many Europeans carry a much stronger moral framework around how money should be earned.
Certain jobs are respectable. Others are looked down on. Making "too much" can even invite suspicion. People praise hard work while quietly side-eyeing extraordinary financial success.
My impression in Thailand was different. Money itself felt morally neutral. The real question wasn't whether someone got rich - it was whether the exchange between buyer and seller was voluntary.
These are personal observations, not universal truths. But they made me question how many of my own beliefs about wealth I'd simply inherited from the culture I grew up in.
The stories we tell ourselves about wealth
Culture doesn't just shape what we do. It shapes what feels normal.
If everyone around you spends forty years working toward retirement, that feels normal.
If everyone around you opens small businesses, reinvests profits, and keeps building wealth throughout life, that feels normal too.
Neither approach is automatically right or wrong. Both have real strengths.
The danger is mistaking familiarity for inevitability. Just because something is normal doesn't make it optimal for your goals.
If your ambition is simply to retire comfortably one day, the traditional European path may suit you fine.
But if your ambition is real financial independence while you're still young enough to enjoy it, you may need a different way of thinking about wealth.
That doesn't mean abandoning Europe.
It means borrowing good ideas wherever you find them.
Financial independence isn't just about money
One of the biggest differences I noticed wasn't how much people earned. It was how they defined financial independence.
In Europe: financial independence usually means having enough money to stop working.
In much of Asia: it means having enough assets, businesses, or investments that working becomes a choice instead of a necessity.
Those are very different goals. One is about leaving the game. The other is about getting better at playing it.
That shows up in how people relate to work itself. Plenty of Western professionals count down the years to retirement. Plenty of entrepreneurs never really retire at all - why would they? Warren Buffett doesn't still work because he needs another paycheck - capital allocation has simply become part of who he is. Li Ka-shing stayed deeply involved in business decisions well into old age. For people like them, wealth became a tool for creating more value, not just funding an exit.
You don't need to become a billionaire for the lesson to apply. The greatest financial freedom usually comes from owning productive assets, not from depending entirely on earned income.
Wealth should remove complexity from your life, not create more of it.
The same principle applies to investing. If you're a business owner, executive or professional whose primary expertise lies somewhere else, spending hundreds of hours learning to manage capital may not be the highest-value use of your time. Your job is to build the business or the career. Your wealth should have its own professional system running in parallel.
See how Sovereign Prosperity approaches active capital management →
Building wealth shouldn't mean postponing life
There's one part of European culture I genuinely admire: Europeans know how to enjoy life. Walk through a European city on a summer evening and you'll find cafés full of friends, parks full of families, people cycling home from work, restaurants full of conversation. That's worth protecting.
In Thailand, I noticed the opposite extreme. Many small business owners worked brutally long days, some for decades straight. There's dignity in hard work - but there's also a cost. If wealth comes at the expense of your health, relationships, or ability to actually enjoy life, something's gone wrong.
Europe could learn: to think more entrepreneurially and take more ownership of its own wealth creation.
Asia could learn: that money is a tool for living well, not an end in itself.
The goal isn't to copy either culture. It's to consciously choose the best ideas from both.
What ambitious professionals should ask themselves
You don't need to move to Bangkok or walk away from your career. But a few uncomfortable questions are worth sitting with:
Is my financial plan built mainly around retirement?
If my salary disappeared tomorrow, what productive assets would keep generating income?
Am I leaning too heavily on governments, employers, or pension systems for my future security?
Do I spend more time improving my career than improving my ability to build wealth?
You don't need instant answers. But they deserve honest reflection. Plenty of professionals get exceptionally good at earning money. Far fewer get good at making money work for them. Those are completely different skills.
Wealth is a skill, not a windfall
One of the biggest misconceptions about wealth is that it belongs to a fortunate few. In reality, it's usually the result of learning a specific set of skills: how businesses actually operate, how capital compounds, how to evaluate opportunities, how to manage risk, and how to think independently instead of following conventional advice just because everyone else does.
That last one matters more than most people realize. The biggest financial opportunities in history rarely looked obvious at the time. They usually required questioning assumptions everyone else accepted without a second thought - about markets, about careers, sometimes about culture itself.
Growing up in Lithuania, I never questioned the retirement model. It just seemed like the responsible thing to do, because it's what everyone around me accepted without question. It took traveling and living somewhere very different to realize there were other ways to think about financial life.
That doesn't mean one culture is superior. It means our beliefs deserve a second look.
Your wealth should work for the life you're building
Building wealth and enjoying life don't have to be opposing goals. That's really the whole point of comparing these two cultures - not to declare a winner, but to notice that both sides accepted a trade-off they didn't have to make.
For people who already have substantial capital, the question isn't simply where to invest. It's how to structure wealth so it can keep growing without demanding more of your time, your attention, or your best years.
That's the problem Sovereign Prosperity exists to solve: intelligent capital management and professional risk management, built so your healthiest decades aren't spent waiting for permission to enjoy what you've earned.
Explore our approach to active capital management
About the author
Tomas Vyšniauskas is a professional trader and founder of Sovereign Prosperity.
Trading full-time since 2021, he manages capital with a focus on disciplined growth and controlled downside.
His work is built around a simple goal: helping people make their existing capital work harder without sacrificing the freedom that wealth is supposed to create.
How fast is your wealth growing?
Select your current annual growth figure:
You're leaving your wealth growth to chance. You're barely outpacing inflation and you're unlikely to grow your wealth to the next meaningful milestone. You're working for the banks but not for yourself. If you'd like to fix this, download our free report - The Silent Wealth Engine - below.
You're doing something right but you're still leaving your wealth growth to chance. You're outpacing inflation but getting the leftovers that are not inspiring. You're still unlikely to grow your wealth to the next meaningful milestone. If you'd like to fix this, download our free report - The Silent Wealth Engine - below.
Congratulations, you're doing well - better than the majority of investors. You're well above the inflation rate. You're likely to grow your wealth to the next meaningful milestone. If you'd like to learn how to maintain your current trajectory in a wiser way or even grow beyond your current limits, download our free report - The Silent Wealth Engine - below.
More from Wealth Intelligence
The European Pension Illusion: Why Retirement Security Is Far Less Certain Than People Think
Alphacore Wealth Advisory: What You Need to Know