You'll spend years comparing mortgage rates. Insurance policies. Investment funds.
But your pension - one of the biggest financial commitments you'll ever make - probably got a single form and a signature.
The cost of that signature is time. Decades of it. Locked away, right when you'd need it most.
In this article:
Why your 30s and 40s are the worst decade to lose control of your capital
What a 40-year pension bet quietly assumes about the future
Why the "retire abroad" dream is less stable than it looks
The hidden cost nobody puts in a spreadsheet
A better question to ask than "how much will I have at retirement"
The Most Valuable Years of Your Life Are the Years You Give Away Control
The years that matter most: your 30s and 40s.
About the author
Tomas Vyšniauskas is a professional trader and founder of Sovereign Prosperity.
Trading full-time since 2021, he manages capital with a focus on disciplined growth and controlled downside.
His work is built around a simple goal: helping people make their existing capital work harder without sacrificing the freedom that wealth is supposed to create.
What happens in them: opportunities appear unexpectedly. A business partnership. A property during a market downturn. A move abroad. A career pivot. An investment in yourself that changes your entire trajectory.
What those opportunities require: access to capital, on short notice.
What a pension does instead: locks away a meaningful chunk of your wealth for decades, right through the years you're most likely to need it.
Consider two people.
One has $250,000 inside a pension account that cannot be touched for decades.
The other has $100,000 of liquid capital under their direct control.
On paper, the first person looks wealthier.
But if an extraordinary opportunity appears tomorrow, who's actually in the stronger position? The person who can act.
At Sovereign Prosperity, we think of true wealth as optionality - the ability to make decisions when life presents opportunities. Money you can't access may still belong to you legally. Economically, its usefulness is severely limited.
A Lesson I Learned Outside Financial Markets
Long before I became a professional trader and capital manager, I worked as a web developer.
The work paid well. Stable clients, stable income, a career path many people would call a success.
Yet something bothered me. My income had little relationship to my actual effort or the value I created. So I went looking for alternatives.
E-commerce. Amazon businesses. Various entrepreneurial ventures.
Most of them shared one thing: extremely long capital cycles. You put money in today and waited months - sometimes much longer - to see anything back. Then you repeated the cycle.
The waiting is what frustrated me.
What I actually wanted was freedom. Not someday. Not after forty years.
That search led me into professional trading and capital management. And the real lesson wasn't about trading - it was about control.
The more control you have over your capital, the more options you have over your life. The less control you have, the more your future depends on systems and institutions you can't influence.
You Are Making a 40-Year Bet on a Future Nobody Can Predict
A pension is a long-term promise. It assumes governments, tax systems, regulations, currencies, and economic structures stay stable enough for the next 30, 40, or 50 years.
That's an extraordinary assumption.
Ask yourself:
What will tax policy look like in 2055?
What will inflation do over the next four decades?
Will retirement ages stay where they are?
What new regulations are coming?
What economic crises haven't happened yet?
What geopolitical shifts are still ahead?
Nobody knows.
Look back forty years - the world of the 1980s barely resembles today's. Entire industries appeared and disappeared. Currencies changed. Governments changed. Markets changed.
Yet plenty of people plan their retirement as if the next forty years will be more predictable than the last forty were.
That doesn't mean pensions are guaranteed to fail. It means betting decades of your capital on political and economic continuity deserves more scrutiny than it usually gets.
Nobody can tell you what tax policy will look like in 2055 - which is exactly why locking your capital into one static, decades-long structure is a bigger bet than it feels like. An active approach to managing capital can actually adapt as conditions change, instead of betting everything on today's rules staying fixed for the next forty years.
See how Sovereign Prosperity approaches active capital management →
The Retirement Dream May Be Less Portable Than You Think
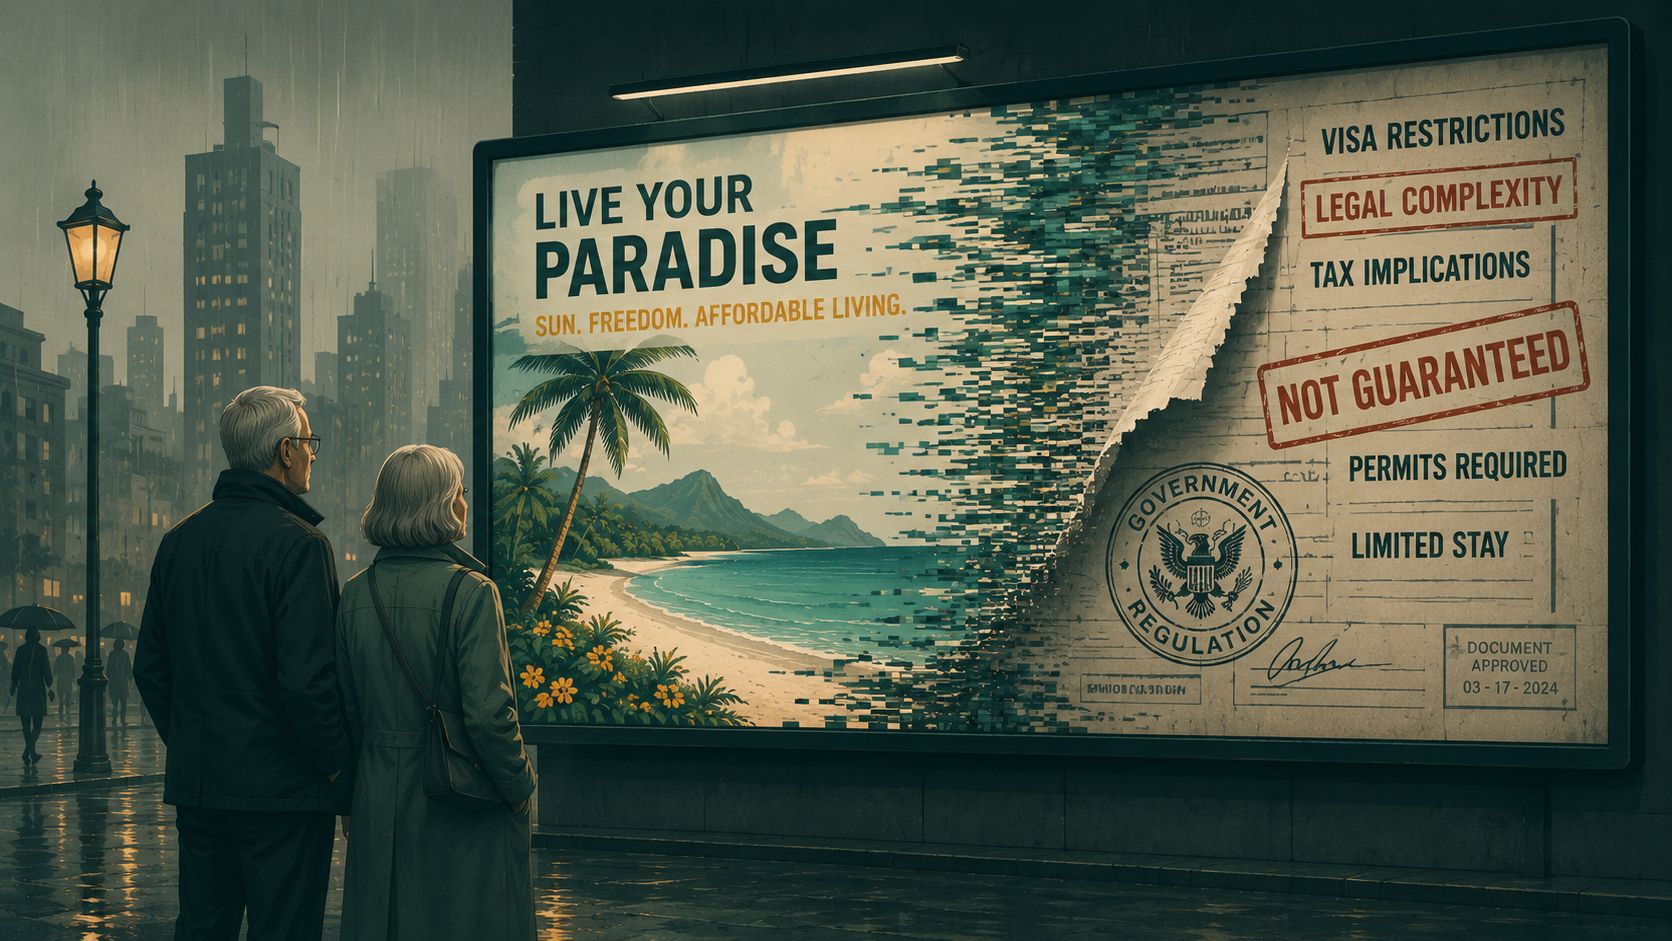
The familiar story: work in a high-income Western country, build a pension, retire somewhere warm and affordable, enjoy life. On paper, it sounds logical.
The catch is that pension systems are political structures - and political structures evolve.
Rules change. Tax treatment changes. Reporting requirements change. Eligibility conditions change. In some jurisdictions, simply relocating abroad can affect your benefits, your taxation, or your admin burden.
The plan that looks perfect today may run under completely different rules decades from now. When your future lifestyle depends on rules that future politicians can rewrite, you're handing over more control than most people realize.
The Hidden Cost Nobody Calculates
The real cost isn't financial. It's psychological.
Traditional financial advice follows a simple formula: work now, sacrifice now, wait now, live later.
The problem is that life doesn't run on that timeline.
Your healthiest years arrive before retirement. Your most energetic years arrive before retirement. Your most adventurous years arrive before retirement. Time doesn't compound - once a decade is gone, it's gone.
This isn't an argument for reckless spending. It isn't an argument against planning for the future either.
The real objective is balance. Future security matters. Present freedom matters too. A good financial strategy should improve your life today while it strengthens your future - not force you to trade one for the other.
Wealth Should Serve Life - Not Replace It
One of the biggest misconceptions about wealth is that it exists purely to maximize the final number.
But what if that number arrives after decades of postponed living? What if financial security shows up after your best opportunities have already passed?
At Sovereign Prosperity, we see it differently. Intelligent capital allocation should create more options, not fewer. The goal isn't just to retire rich. The goal is to live rich.
That means building wealth responsibly. Respecting risk. Staying away from financial fantasies and overnight-riches schemes.
But it also means questioning systems that ask you to surrender flexibility for decades on the hope that the world stays predictable. As I tell aspiring traders and investors often - life is happening right now. Your best years aren't meant to be spent waiting for permission to enjoy them.
A Better Question to Ask
Most people ask: "How much money will I have when I retire?"
A more useful question is: "What kind of life will my financial decisions let me live between now and retirement?"
The real question isn't how much you'll have at 65. It's how much control you have over your capital between now and then.
For professionals and business owners with real capital to deploy, that kind of control usually isn't something a generic pension plan or a hands-off model portfolio delivers. It takes an active, professional approach to managing capital - built around your timeline, not an actuarial table.
That's what Sovereign Prosperity was built to provide.
Explore our approach to active capital management
No pressure. No unrealistic promises. Just an honest conversation about what professional capital management could mean for your future.
About the author
Tomas Vyšniauskas is a professional trader and founder of Sovereign Prosperity.
Trading full-time since 2021, he manages capital with a focus on disciplined growth and controlled downside.
His work is built around a simple goal: helping people make their existing capital work harder without sacrificing the freedom that wealth is supposed to create.
How fast is your wealth growing?
Select your current annual growth figure:
You're leaving your wealth growth to chance. You're barely outpacing inflation and you're unlikely to grow your wealth to the next meaningful milestone. You're working for the banks but not for yourself. If you'd like to fix this, download our free report - The Silent Wealth Engine - below.
You're doing something right but you're still leaving your wealth growth to chance. You're outpacing inflation but getting the leftovers that are not inspiring. You're still unlikely to grow your wealth to the next meaningful milestone. If you'd like to fix this, download our free report - The Silent Wealth Engine - below.
Congratulations, you're doing well - better than the majority of investors. You're well above the inflation rate. You're likely to grow your wealth to the next meaningful milestone. If you'd like to learn how to maintain your current trajectory in a wiser way or even grow beyond your current limits, download our free report - The Silent Wealth Engine - below.
More from Wealth Intelligence
Minimum Investment: What It Means for Serious Wealth
The "Enough Number": How Much Wealth Actually Improves Your Life?